Table of Content
Capital gains on sale of primary residence are often excluded up to $250,000 if your parents lived there 24 of the last 60 months before closing.
That single rule sets the deadline for the whole decision. Because the test looks back five years from the sale date, a parent who moves out has roughly three years to sell before the residence requirement stops being met. The IRS exclusion is up to $250,000 of gain for a single filer and up to $500,000 for a married couple filing jointly.
There is also an exception written specifically for families in this situation, and it changes the answer for many of them. Time spent in a licensed care facility can count as residence, which takes the pressure off the calendar. The details are below, along with the Medicaid rules that run on a completely different clock.
How Does the Capital Gains Exclusion Work on a Parent's Home?
Two separate tests decide it, and both have to be satisfied within the five years ending on the date of sale.
The Ownership and Residence Tests
The ownership test is met if the home was owned for at least 24 months out of the last five years. The residence test is met if it was used as a main home for at least 24 months of the previous five years. Those 24 months do not have to be one continuous block, and the two tests can be satisfied during different two-year periods, so long as both fall inside that five-year window.
For a married couple filing jointly, only one spouse has to meet the ownership test, while both have to meet the residence test individually. Short absences such as vacations still count as time lived at home.
The Care-Facility Rule Most Families Miss
This is the part worth reading twice. IRS Publication 523 states that if a person becomes physically or mentally unable to care for themselves, and used the home as a main residence for at least 12 months in the five years before the sale, then any time spent living in a care facility counts toward the two-year residence requirement, provided the facility is licensed by a state or other political entity to care for people with that condition.
In plain terms, a parent who lived at home for a year and then moved into a licensed facility may still meet the residence test years later. That is a very different planning picture from the three-year rule of thumb, and it is the first thing a tax preparer should check.
Selling Before Two Years Are Up
A sale that misses the full test is not automatically taxable on the whole gain. A partial exclusion is available when the primary reason for the sale fits certain categories, and a health-related move is one of them. That includes moving to obtain or provide medical or personal care for a family member with a disease, illness, or injury, and cases where a doctor recommended a change of residence for a health problem. Parents, grandparents, and children all count as family members for that rule.
Why Does Selling Before the Move Appeal to Families?
One set of bills instead of two, and a parent who is still able to take part in the process.
Selling first means the proceeds are available before the first month of care is invoiced, so nobody is covering assisted living out of savings while waiting on a buyer. It also means your parents can make decisions about their own belongings rather than having those decisions made for them later.
The practical argument is just as strong. Sorting a house while its owner is still living there is slower but far less painful than clearing it out after the fact, and it avoids the situation where family members are opening drawers and guessing about what matters.
The cost is flexibility. Once the house is gone, a community that turns out to be a poor fit has no fallback, and there is no quiet way to reverse the move. Some families accept that trade; others will not.
Why Does Waiting Sometimes Make More Sense?
Because the first few months tell you whether the community is right, and because the clock is usually not as tight as it feels.
A trial period has real value. Appetite, sleep, mood, and willingness to join activities are hard to predict from a tour, and a parent who hates the place in month two is much easier to move if the house has not been sold. Comparing options is easier with the assisted living guide open alongside the tours, since what looks similar on a brochure often differs in staffing and size.
Scale is part of that fit. A six-bed home in a residential neighborhood runs differently from a sixty-bed community, and small group homes are frequently the cheaper option as well as the quieter one. Families who need help narrowing a list often work with a placement service such as Completely Senior, which handles assisted living, memory care, and board and care searches across the San Fernando Valley and East Ventura County.
Waiting also keeps the option of going back. If the move was triggered by one bad month rather than a permanent decline, returning home with modifications and more support is sometimes the better outcome, and home modifications that prevent falls are cheaper than a year of residential care.
The medical side of the move can be handled at the house too. California communities generally require a physician's report before admission, and a doctor who makes house calls can complete that assessment without moving a frail parent to an office.
What Happens While the House Sits Empty?
Two households are funded at once, and the vacant one gets more expensive the longer it stands still.
The mortgage, property taxes, insurance, utilities, and yard care all continue, and insurers often treat an unoccupied house differently from an occupied one, which is worth a call before the keys come out. Add the cost of someone checking on it, and the monthly carry is rarely as small as families expect.
That gap between the first care invoice and the closing date is a real cash-flow problem, and it is the reason bridge financing exists for this situation. Senior Home Transitional Services works on exactly that seam, with senior bridge loans, home equity conversion mortgages, and real estate solutions for families in the west San Fernando Valley.
Whatever route is chosen, the number to work out first is the monthly shortfall: care cost minus income, multiplied by the realistic number of months to sell in that market. A decision made against that figure tends to hold up better than one made against a feeling.
Selling Before Versus Selling After, Side by Side
The comparison below sets the two timings side by side on the points families actually argue about. It is a framework for the conversation rather than a recommendation, since the right answer depends on cash flow, the parent's health, and the market.
|
Selling Before the Move |
Selling After the Move |
|---|---|
|
One set of housing costs instead of two |
Mortgage, taxes, insurance, and utilities keep running while it is empty |
|
Your parent is there to sort belongings and sign documents |
Clearing out falls to family, often from another state |
|
No trial period; the decision is hard to reverse |
A few months to see whether the community actually suits them |
|
Residence test is clearly met at closing |
The 24-of-60-month residence clock keeps running after the move |
|
Proceeds are in hand before the first invoice arrives |
Care has to be funded from savings or income until the sale closes |
How Does Medicaid Change the Timing?
Medicaid runs on its own calendar, and that calendar punishes anyone who tries to move assets quickly. If long-term Medicaid coverage is even a possibility, the house decision belongs to a lawyer before it belongs to a realtor.
The Five-Year Look-Back
A 2025 paper in the Journal of Applied Gerontology describes the Medicaid look-back period as a rule that prohibits applicants in most states from gifting or transferring assets to relatives or charitable organizations within the five years before enrollment. Applicants who do it are denied, and may have to rely on family to pay for care until they can reapply. The same paper notes most states cap countable assets at $2,000 for an individual and $3,000 for a married couple.
So signing the house over to an adult child is not a shortcut. It is the specific move the look-back exists to catch, and the penalty lands at the worst possible moment, when care is already being delivered and someone has to pay for it.
What the Spend-Down Numbers Look Like
Spending down to Medicaid is a common ending rather than a rare one. A study published in JAMA Network Open in December 2025 followed 191,416 nursing home residents and found that 16.4% of those who entered in 2018 without Medicaid had spent down their assets and enrolled in Medicaid by 2022, with a mean time to spend-down of 6.1 months.
That figure reframes the house question. For a long stay, the sale proceeds may be funding care for a defined stretch rather than indefinitely, which makes how the money is held and spent a legal question as much as a financial one.
Who Should You Talk to Before You List?
An elder law attorney first, then a tax preparer, then the real estate agent. Reversing that order is how families create problems that cost more than the commission.
The National Institute on Aging makes a similar point about professional help, noting that some ways of paying for long-term care carry consequences for taxes and for any inheritance, and listing accountants, financial planners, investment advisors, tax preparers, and attorneys as the people worth consulting. It also notes that professional care in assisted living is almost always paid out of pocket, with Medicaid covering some costs in some states.
Three questions are worth bringing to that first meeting. Does the care-facility residence rule apply to our situation? Is Medicaid realistically in the picture within five years? And who holds a valid power of attorney for finances, since without one a sale can stall for months.
Clearing Out a House From Another State
Break it into trips with one job each, rather than trying to empty a house in a single weekend. Distance makes this the part families dread most, and it is the part that benefits most from a plan.
Start with documents, not furniture. Deeds, insurance policies, tax returns, the mortgage statement, and anything with an account number on it should leave the house on the first trip. Those are the items that stall a sale when they go missing.
Then photograph every room before anything moves. A photo record settles sibling disagreements later and gives an estate sale company something to quote against without a site visit. Hiring locally for hauling, cleaning, and staging usually costs less than repeated flights.
Keep one box of things that go with your parents, chosen with them if possible, and let the rest be decided on paper rather than in the hallway. More practical pieces on senior care and household decisions sit in the care guide library.
Putting the Two Decisions in Order
Separate the care decision from the real estate decision, and make them in that order. The move is driven by safety and health; the sale is driven by cash flow, tax rules, and Medicaid exposure.
A workable sequence looks like this:
Confirm the level of care the parent actually needs and secure a place.
Ask an elder law attorney about Medicaid exposure and the five-year look-back.
Have a tax preparer check the ownership, residence, and care-facility rules against the real dates.
Calculate the monthly shortfall and decide how long the house can be carried.
List when the numbers, not the emotions, say it is time.
Done in that order, the capital gains question stops being the thing that drives the move and becomes what it should be: one input among several, with a deadline you can see.
FAQ
-
Often yes. If a Form 1099-S arrives from the closing, the sale has to be reported even when the whole gain is excludable, and it also has to be reported whenever part of the gain cannot be excluded. Keeping the closing statement and the records of past improvements makes that filing much easier.
-
Yes, but not back to back. The exclusion can be taken only once in any two-year period, so a parent who excluded gain on another home within the two years before this sale generally does not qualify again. This catches families who downsized recently and are now moving a second time.
-
The two tests are treated differently for a married couple filing jointly. Only one spouse has to meet the ownership requirement, but each spouse has to meet the residence requirement individually for the full exclusion. A couple where one spouse moved into care years earlier should have the numbers checked before listing.
-
It adds a separate set of rules. Rental and business use of a home brings in depreciation recapture and nonqualified-use calculations, which the IRS covers in its own sections of Publication 523. Renting also turns the family into a landlord at a distance, so raise it with a tax preparer before signing any lease.
-
For most families, no. Only a small minority of older adults hold a private long-term care policy, and most ordinary health or disability policies include limited long-term care benefits at best. Check the actual policy language rather than assuming, since the daily benefit and waiting period decide how much pressure the house is really under.
-
Generally not. Medicare does not cover long-term services and supports, and professional care in assisted living is almost always paid out of pocket, with Medicaid covering some costs in some states for people who qualify. That gap is the reason the timing of the sale matters so much.
Sources Used
Asset Spend-Down and Medicaid Enrollment in Nursing Homes – JAMA Network Open (2025)
Paying for Long-Term Care – National Institute on Aging (2023)
Perspectives on the Challenges of Planning for and Accessing Long-Term Dementia Care Services Through Medicaid and Medicaid Waivers – Journal of Applied Gerontology (2025)
Publication 523 (2025), Selling Your Home – Internal Revenue Service (2025)
Topic no. 701, Sale of your home – Internal Revenue Service (2026)
Property (basis, sale of home, etc.) 4 – Internal Revenue Service (2026)
Understand Medicaid's Look-Back Period; Penalties, Exceptions & State Variances – American Council on Aging (2026)
Written by Sofiia Puhach
October 26, 2026
You May Also Like
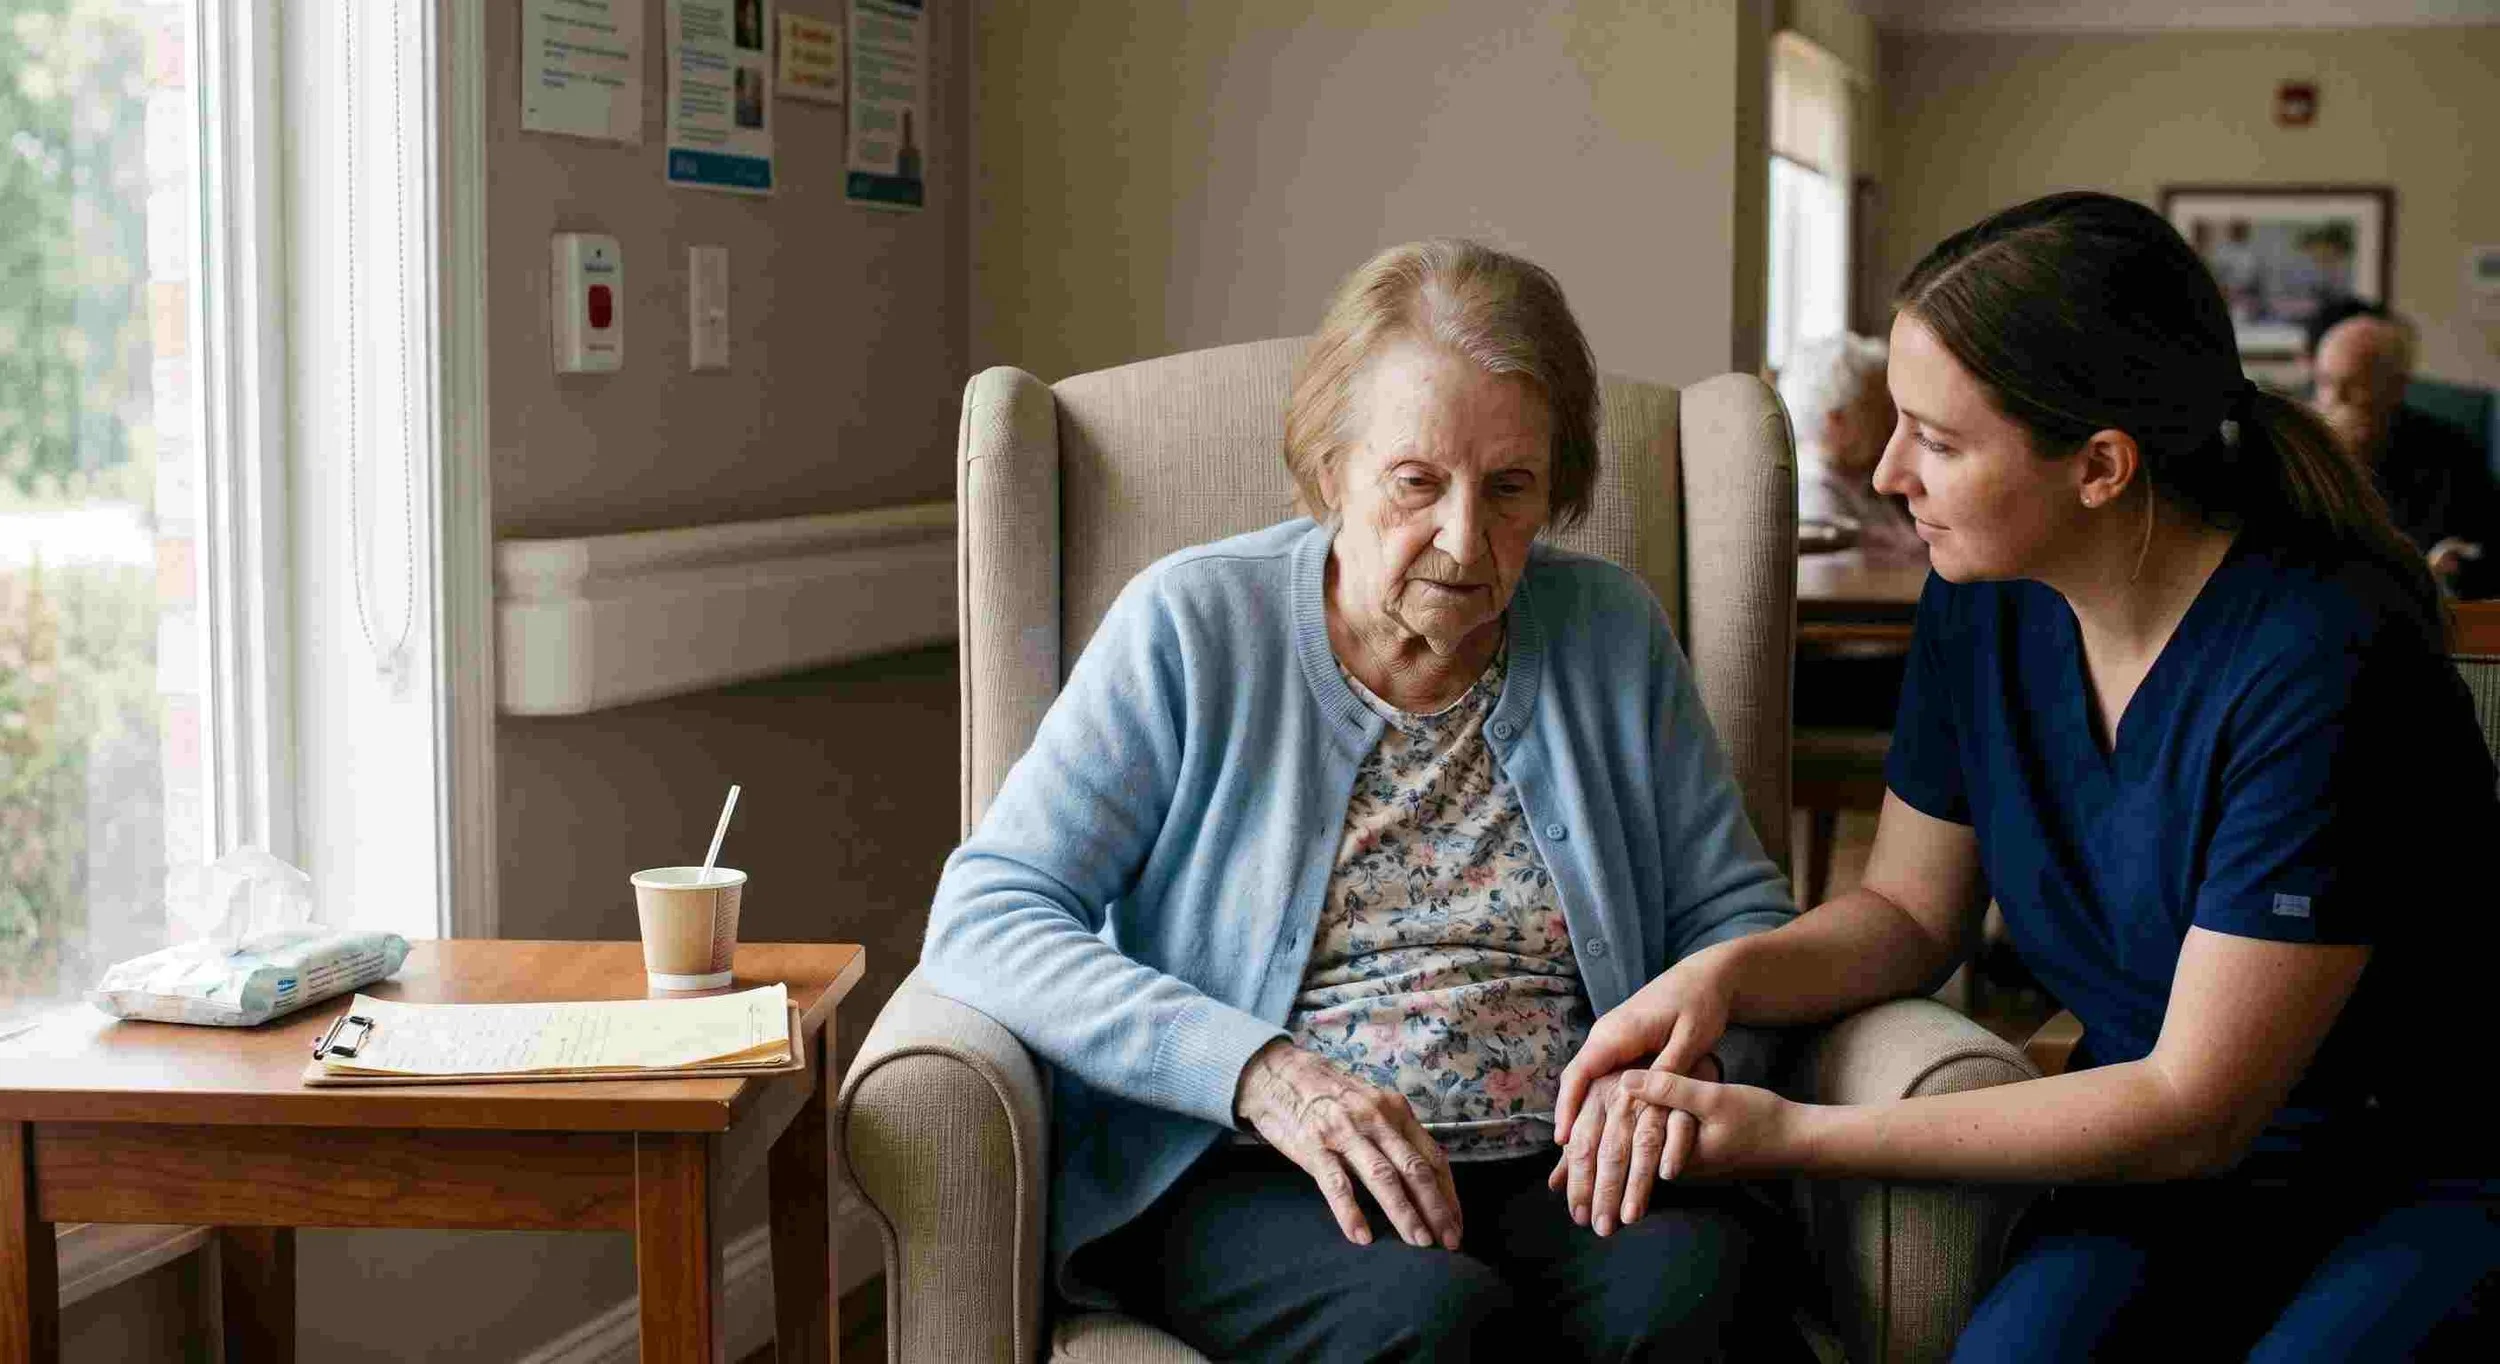
Moving out starts a clock: the home must have been a residence 24 of the last 60 months to qualify.